Public Adjusters in Florida
Facing property damage in Florida? We represent residential and commercial policyholders throughout the insurance claim process to secure the maximum settlement owed to you.

Florida Insurance Adjusting
Living & Owning Property in FL
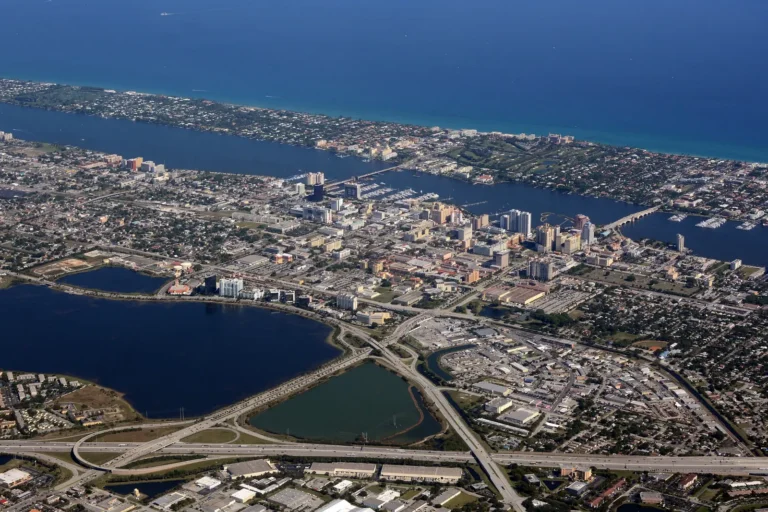
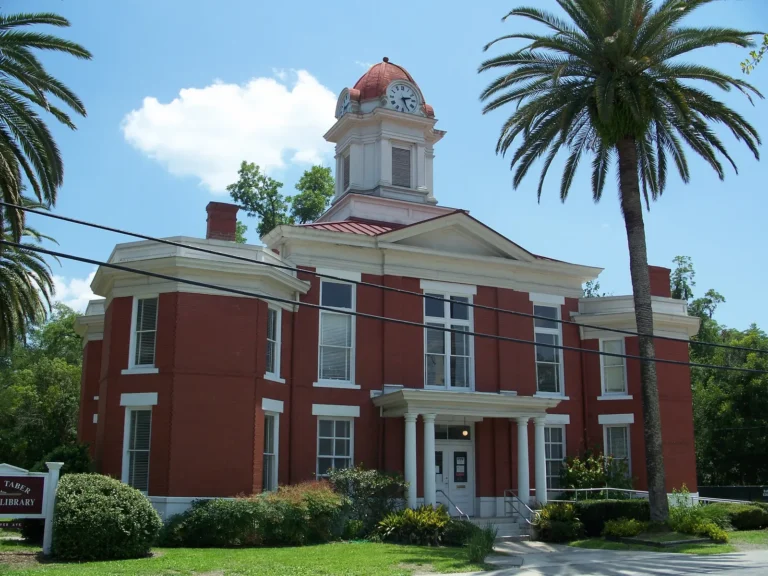
Photo: Matt Kieffer from London, United Kingdom via Wikimedia Commons (CC BY-SA 2.0)
How Public Adjusting Works in FL
Fighting for Policyholders
Public adjusters advocate on your behalf against greedy insurance companies, fighting to secure the maximum settlement you’re entitled to.
Florida Claim Dispute Resolution
Denied or Underpaid Claim?
Insurance companies profit by minimizing payouts. If your FL property claim was delayed, denied, or underpaid, our licensed adjusters reopen and renegotiate your claim.
Licensed Public Adjusters Serving Florida
Our team of Public Adjusting experts are licensed by the Department of Insurance in Florida to advocate directly for property owners.
-
Founder & Owner
-
Director of Operations
-
Claims Manager
-
Loss Estimating Manager
-
Operations Manager
-
Public Adjuster
-
Public Adjuster
-
Public Adjuster
-
Public Adjuster
-
Field Public Adjuster
-
Public Adjuster
-
Field Public Adjuster
-
Field Public Adjuster
-
Public Adjuster
-
Field Public Adjuster
-
Scheduling Coordinator
-
Lead Intake Specialist
-
Compliance & Operations Coordinator
-
Accounting
-
Accounting
Florida Public Adjusting FAQs
A public adjuster is a licensed professional who represents you, the policyholder. They review damage, interpret your policy, prepare and file the claim, negotiate with the insurer, and work to maximize your settlement under your coverage.
Yes. Florida law defines a “public adjuster” and requires licensing under § 626.854. Public adjusters must comply with the licensing procedures set by the Florida Department of Financial Services (DFS) and meet continuing education, bonding, and regulatory standards.
- 10% of your settlement if the claim is based on a declared state of emergency for the first year.
- Up to 20% for non-emergency or supplemental claims.
- Your property loss is large or complex (hurricane, flood, multiple claim layers)
- You received a low offer from your insurer
- You lack the time or expertise to document and negotiate your claim
- Be in writing and titled “Public Adjuster Contract”
- Include the adjuster’s business name, license number, and contact info
- Display the percentage compensation in bold, large type
- Specify the type of claim (emergency, non-emergency, supplemental)
- Provide you with a copy upon signing and send one to the insurer within 7 days.
Yes — in many cases. If settlement seems insufficient or some damage was overlooked, you can engage a public adjuster to review, document missed items, and negotiate supplemental payment — provided the adjuster’s contract is drafted correctly and you still have valid coverage.
- Adjusters cannot charge for claim payments made before the contract.
- Solicitation is restricted to Monday through Saturday, 8 a.m.–8 p.m. for residential claims.
- Offering inducements (gifts, contractor referrals with kickbacks) is prohibited.
- Hurricane or windstorm damage (roof, siding, flooding)
- Flood and water intrusion (especially after heavy rains and coastal storms)
- Fire, smoke, and mold damage
- Multi-layer or business interruption claims
Yes, especially when your claim is large, complex, or contested. Statistically, policyholders who use qualified public adjusters often receive higher settlements and smoother negotiations. Make sure you hire a licensed professional with Florida-specific experience.
Visit the Florida Department of Financial Services website to look up any adjuster’s license status, disciplinary history, or bonding. Make sure they hold a 3-20 Public Adjuster license or equivalent.
Public Adjusting in Every City in Florrida
Facing Property Damage in Florida?
Don't handle the insurance company alone. Contact Noble Public Adjusting Group today for a comprehensive policy and damage appraisal.