Hurricane Isaias: Insurance Claim Help & Damage Guide
Monitoring Hurricane Isaias
Hurricane Isaias
As Hurricane Isaias tracks toward the Gulf Coast, property owners across the Florida Panhandle, Louisiana, and the Central Gulf Coast face severe risks of wind uplift, roof leaks, and catastrophic flood damage. Protecting your insurance recovery starts before temporary repair crews arrive. Request a free, immediate claim consultation with our licensed public adjusters below to ensure your settlement is protected from day one.
Let us handle the insurance company for you. Fill out your details below to get started with Noble.
Tropical Storm Isaias Rapidly Organizing in the Gulf
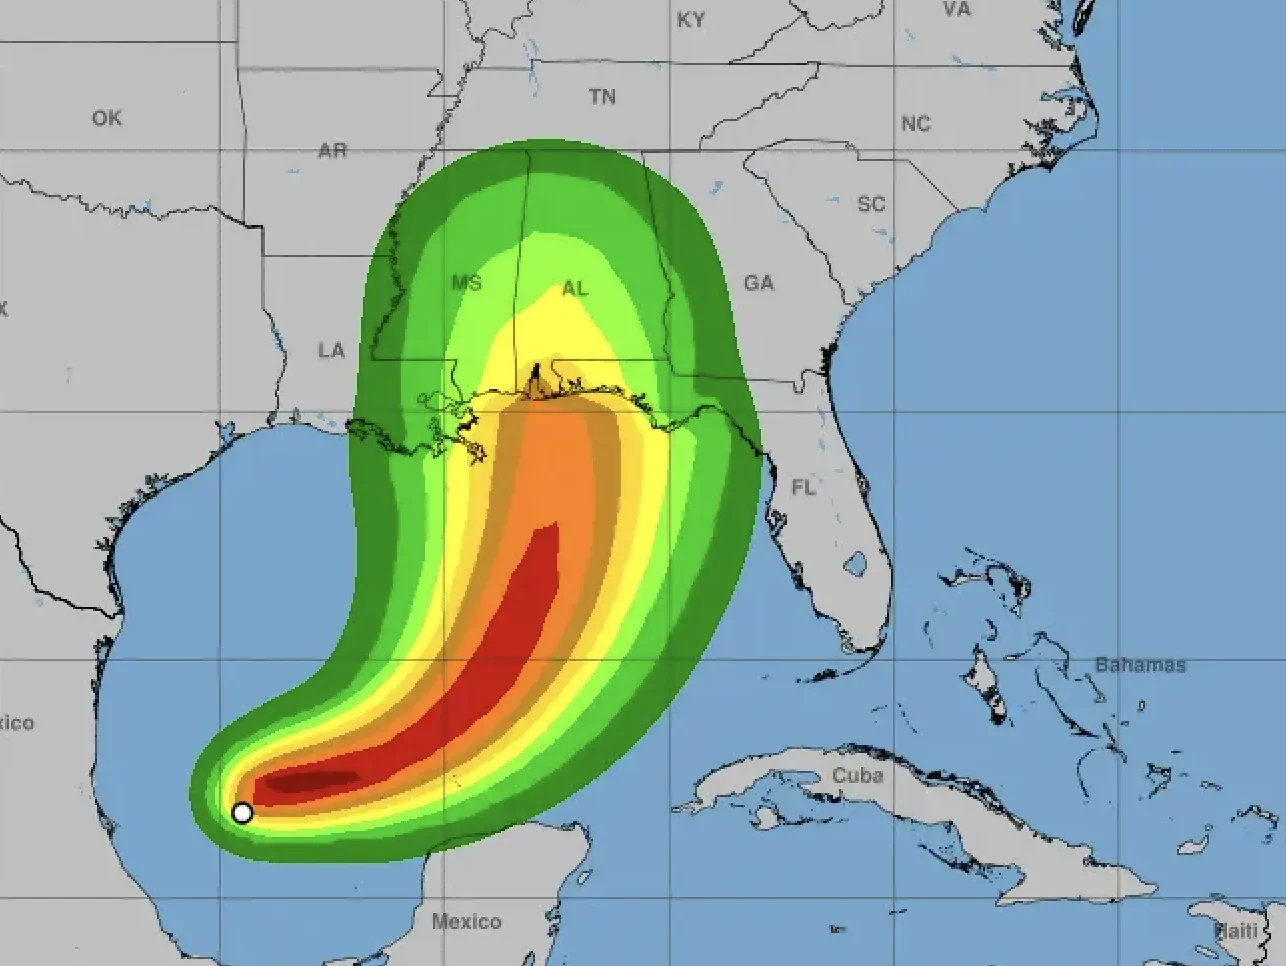
Last Updated: Oct at 10:36 AM CDT
The National Hurricane Center has officially upgraded the system in the southwestern Gulf to Tropical Storm Isaias. Isaias is forecast to strengthen as it tracks north-northeast toward the northern Gulf Coast, with potential to reach hurricane intensity before making landfall late this week.
Regardless of peak wind strength, tropical moisture will drive severe flash flooding across low-lying communities in Louisiana, while gusty winds and heavy rain threaten roof damage and water intrusion across the Florida Panhandle.
Areas Under Close Monitoring
-
Louisiana & Central Gulf Coast: High risk of severe flash flooding from 5–10 inches of rain, municipal drainage backups, and 3–5 ft storm surge.
-
Florida Panhandle (Pensacola to Panama City): Exposure to 60+ mph wind gusts, roof uplift, and wind-driven rain penetrating exterior walls and window seals.
-
Florida Big Bend & West Coast: Onshore wind flow driving 2–4 ft coastal surge, beach erosion, and localized tidal flooding across waterfront properties.
Pre-Landfall Claim Guidance
Critical Steps to Protect Your Property Before and After Landfall
-
Document Pre-Loss Baseline Conditions: Take date-stamped video of your property, including roofs, HVAC units, windows, and interiors before winds pick up to establish verifiable proof of pre-loss condition.
-
Mitigate Rapid Mold & Moisture (First 24 to 48 Hours Post-Storm): Coastal humidity drives rapid mold growth. Tarp damaged roofs and begin water extraction immediately if safe, photographing all waterlines before cleanup.
-
Log All Emergency Mitigation & Expenses: Keep itemized receipts for tarps, dehumidifiers, board-ups, and generator fuel. Insurance policies may cover reasonable protective measures.
Gulf Coast Hurricane Damage Claims
Residential, Commercial, & Condominium Expertise
Commercial & Resorts
Hotels, Plazas & Hospitality
Maximize Business Interruption (BI), extra expense calculations, and utility service interruption claims. We audit full building envelopes structural glass failures, and flat roof membranes across retail, warehousing, and resort properties.
Condo Associations (HOA/COA)
Condo Boards & Multi-Family
Reconcile complex HOA master policies against individual unit owner claims. We handle common element roof uplift, elevator shaft water damage, and enforce mandatory ordinance and law code upgrades.
Residential & Estates
Homeowners & Luxury Claims
Protect your family home from rushed, surface-level carrier inspections. We uncover hidden roof deck uplift, attic insulation saturation, and window seal failures, fighting for what you are actually owed rather than cheap, mismatched spot repairs.
Beware of These Common Post-Storm Traps
-
Improper Application of Hurricane Deductibles: Carriers often apply a costly 2% to 5% percentage hurricane deductible to storm damage instead of honoring your standard, lower all-other-perils deductible.
-
The "Rising Water" Blame Shift: Insurance company adjusters frequently label interior water damage as excluded flood or rising groundwater to deny claims caused by wind-driven rain entering through compromised roofs and windows.
-
Piecemeal Spot Patching: Insurers frequently write lowball estimates to patch a few cracked tiles, shingles, or siding panels. In reality, discontinued materials, product brittleness, and repairability challenges can make spot repairs impossible, which may necessitate a complete roof replacement depending on state guidelines and policy terms.
-
Predatory Emergency Repair Contracts: Beware of storm-chasing contractors who arrive days after a disaster offering emergency repairs and pushing rushed agreements that trick you into signing over your entire insurance check for a single repair.
Next Steps: Navigating Your Claim After Landfall
Once the immediate danger has passed and safety measures are in place, the official insurance claim process begins. Taking the right steps after the first 48 hours can make a multi-thousand-dollar difference in your final recovery. To avoid falling victim to common insurance carrier tactics or contractor scams, we encourage you to call Noble before filing your claim. Our licensed experts are ready to guide you through the entire process and serve as your personal advocate during this challenging time. Don’t hesitate, reach out today!
Did Hurricane Isaias Damage your Property?
Insurance companies work to maximize corporate profits. We work for YOU, fighting to secure you what you're owed. Contact us today for a complimentary claim review!